Most budgets fail not because the numbers are wrong, but because the structure asks too much of human willpower. You set a monthly limit for dining out, another for clothes, another for random household purchases — and then life happens across thirty unpredictable days. By day twenty, you've lost track of where you stand, a few unplanned purchases have blurred the lines between categories, and the whole system quietly collapses into guesswork.
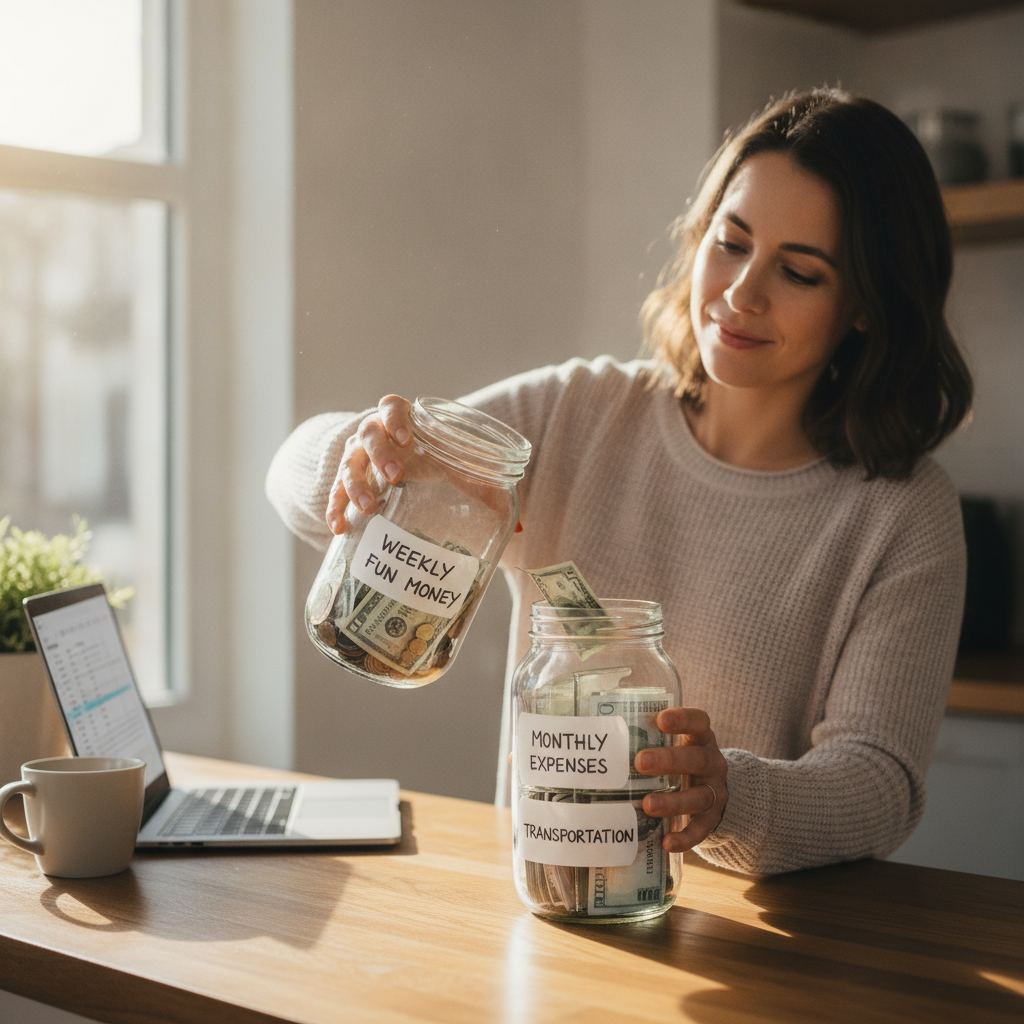
The weekly personal allowance method works differently. Instead of carving your discretionary spending into narrow category buckets, you pull a fixed weekly sum — cash or a dedicated debit card like one from Chime or a simple checking sub-account — and that amount covers everything personal and flexible for the week. When it's gone, it's gone. The constraint is real, immediate, and simple to feel. Category limits live in a spreadsheet; a weekly allowance lives in your hand.
How Does a Weekly Allowance Actually Work?
The mechanics are straightforward. You take your total monthly discretionary budget — the money left after fixed expenses, savings transfers, and bills — and divide it by 4.3 (the average number of weeks in a month). That number becomes your weekly personal spending limit. Some people move this amount to a separate account each Monday; others withdraw cash. The key is that the money is physically or digitally separated from your main account so you can't accidentally dip into next week's share without noticing. Apps like YNAB can help you track this if you prefer digital, but the method works just as well with an envelope.
Why Do Category Limits Often Fall Short on Their Own?
Category-based budgeting is a solid foundation, but it has a structural weakness: categories are abstractions. When you tell yourself you have a hundred and fifty dollars for dining this month, that number doesn't feel real at the start of the month — it feels enormous. By week three, it feels dangerously small, but the damage is already done. Weekly allowances compress the time window so the scarcity is felt immediately rather than retroactively. The psychology shifts from "I've been good all month, I deserve this" to "I've got forty dollars left this week, let me think about this." That shorter feedback loop is where the behavioral change actually happens.
What Should Your Weekly Allowance Actually Cover?
Your allowance should cover anything discretionary and variable — coffee runs, lunches out, impulse buys, entertainment, Uber rides that aren't strictly necessary, small clothing purchases, and similar spending that doesn't have a fixed billing date. It should not include rent, utility bills, subscriptions with set monthly charges, or your savings transfers. Those stay in the main budget and get paid as usual. The weekly allowance is specifically for the flexible, day-to-day choices where overspending tends to happen organically. Keeping the scope clear stops you from raiding the allowance to cover things that should have been planned for separately.
How Do You Handle Weeks With Bigger Planned Expenses?
Some weeks cost more than others — a friend's birthday dinner, a concert, a seasonal clothing refresh. The allowance system accommodates this without falling apart. If you know a big week is coming, carry forward unspent money from the week before. Most people find that lean weeks naturally create a small buffer without any deliberate effort, just because the weekly ceiling makes them more mindful. For larger planned events, you can earmark a portion of the following week's allowance in advance, treating it as a small sinking fund within your weekly rhythm. The structure bends without breaking.
Why Does a Shorter Spending Window Change Behavior?
Budget psychology research consistently points to the same pattern: people make better spending decisions when the feedback is close in time. Monthly budgets stretch the consequence so far into the future that the connection between today's choice and tomorrow's shortfall feels abstract. A weekly limit makes the trade-off immediate. Spending thirty dollars on lunch today means thirty fewer dollars for the rest of the week — and you feel that concretely. This isn't about guilt or deprivation; it's about giving your brain the information it needs at the moment a decision is being made rather than two weeks after the fact.
How Do You Set the Right Weekly Number Without Undershooting?
One of the most common mistakes is setting the allowance too low and burning out on the system within a month. Start by tracking your actual average weekly discretionary spending for three or four weeks without changing anything — tools like Monarch Money or a simple spreadsheet work well for this. Use that baseline to set a realistic starting number, even if it feels a little generous. You can tighten it gradually once the habit is established. A system you can sustain at ninety percent effectiveness beats a perfect system you abandon after three weeks.
What Happens to Leftover Money at the End of the Week?
This is where the allowance method gets genuinely motivating. You have a few options: roll the leftover into next week for a slightly cushier spending window, transfer it straight into savings, or let it accumulate in a small fun fund for something you've been wanting. All three outcomes reward restraint in a tangible way. Unlike category budgets where unspent money just disappears back into the monthly total without any sense of personal win, the weekly format makes every dollar saved feel like something you actively chose. That feeling compounds over time and makes the habit easier to sustain.
How Do You Keep the System Simple Enough to Actually Use?
Simplicity is the whole point. If tracking your weekly allowance requires a complex spreadsheet or twenty minutes of reconciliation every evening, you'll stop doing it. The goal is one number, one account or envelope, one weekly reset. Chime, SoFi, and most online banks let you open a secondary spending account in minutes, which makes the separation clean without adding friction. Check your balance twice a day — morning and evening — so you always know where you stand. That's genuinely all the maintenance this system needs. The constraint does most of the work automatically.
The weekly allowance isn't a replacement for a full budget — it sits on top of one, handling the messy discretionary layer that categories alone struggle to contain. Starting is simple: calculate your monthly discretionary total, divide by 4.3, and move that amount somewhere separate this coming Monday. Give it four weeks before you judge it. Most people find that the clarity alone — knowing exactly what's available right now — does more for their spending than any spreadsheet ever did.