Most financial advice treats the emergency fund as a single, undivided pool of money — a number you hit and then leave alone. That framing is straightforward, but it misses something important about how emergencies actually work and how idle money quietly loses ground to inflation over time. A two-tier approach, one that separates immediately accessible cash from a higher-earning savings layer, addresses both problems without requiring complicated financial products or a large income. It's a structural shift, not a sacrifice, and it's one of the more practical changes a person can make to how they hold their safety net.
The Problem With Keeping Everything in One Account
A traditional emergency fund parked entirely in a standard checking or basic savings account is safe in the narrow sense — the money is there — but it isn't working. Interest rates on standard accounts at institutions like Chase or Bank of America have historically lagged well behind inflation, meaning that a fund left untouched for a year or two loses real purchasing power. At the same time, holding the full amount in a high-yield account creates a different friction: some of those accounts impose transfer delays or withdrawal limits that make them less useful in a moment of genuine urgency. Neither extreme serves the account holder well on its own.
How the Two-Tier Structure Actually Works
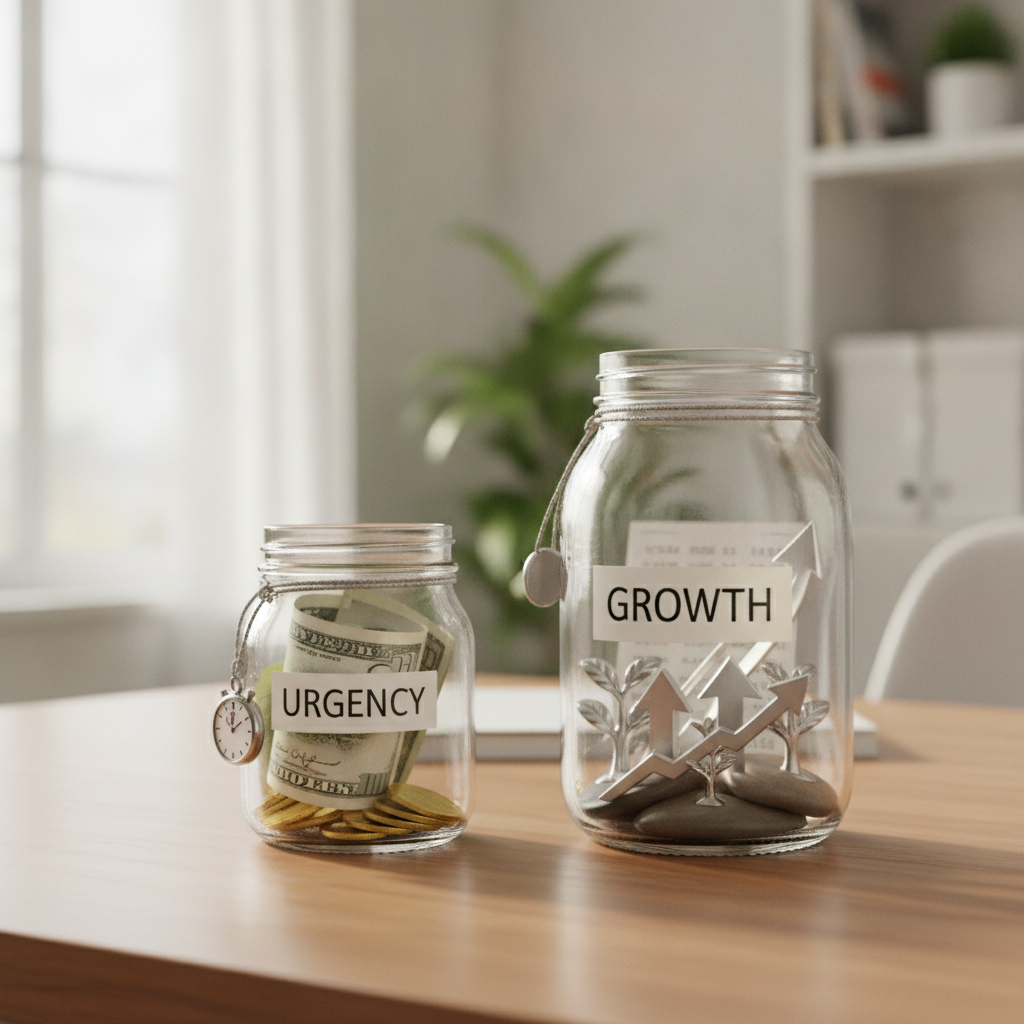
The logic behind splitting an emergency fund is straightforward. The first tier holds a smaller amount — roughly one to two months of essential expenses — in a liquid account that connects directly to a checking account or debit card. This is the immediate-response layer, available within hours, no transfer window required. The second tier holds the remainder, typically three to four months of expenses, in a high-yield savings account through institutions like Ally, Marcus by Goldman Sachs, or SoFi, where the annual yield is meaningfully higher. The two tiers function as a front door and a vault: the front door handles the sudden, the vault grows quietly behind it.
Defining What Belongs in the Liquid Tier
The liquid tier isn't meant to cover every possible emergency — it's calibrated to the most common and time-sensitive ones. A car repair that needs to happen before Monday, an urgent prescription, a broken appliance in the middle of winter: these are the scenarios that require same-day access. One to two months of core expenses — rent or mortgage, utilities, groceries, minimum debt payments — is generally enough to absorb these without disruption. Keeping more than that in a low-yield account is inefficient. Keeping less creates the risk of turning to credit cards in moments when they're least affordable to carry.
What the High-Yield Tier Contributes Beyond Interest
The second tier does more than earn a higher rate. Placing the bulk of an emergency fund in a separate, slightly less accessible account creates a meaningful psychological barrier against casual spending. When the money isn't visible in a day-to-day checking balance, it doesn't factor into spending decisions the same way. Apps like Ally or Marcus present the account as clearly separate from spending money, which reinforces the distinction. The interest earned, while not dramatic, is genuinely compounding over months and years — and in a period of stable or elevated rates, the gap between a high-yield account and a standard savings account can represent a material difference over a two- or three-year horizon.
Building the Two Tiers Without Starting From Zero
For anyone who doesn't yet have a full emergency fund in place, the two-tier structure can be built incrementally rather than all at once. The practical sequence is to establish the liquid tier first — reaching one month of essential expenses in a connected account before opening the high-yield account. Once that floor is in place, every additional contribution goes toward the second tier until the full target is reached. If you're automating savings, you can direct one transfer to the liquid account until it's funded, then redirect the automation to the high-yield account. The structure doesn't require a large lump sum; it responds well to the kind of slow, consistent building that most people are already capable of.
Maintaining the Balance as Circumstances Change
A two-tier emergency fund isn't a set-and-forget arrangement. As income grows, as fixed expenses shift, or as household size changes, the target amounts for both tiers should be revisited. A common pattern is to keep the liquid tier stable while allowing the high-yield tier to expand — growing the vault without changing the front door. When the liquid tier gets drawn down in an actual emergency, the recovery sequence is to refill it first before resuming contributions to the high-yield account. This keeps the most time-sensitive layer whole while the longer-term reserve continues earning. Revisiting the structure once or twice a year, perhaps alongside a broader budget review, keeps both tiers calibrated to current reality.
The opening observation holds through every layer of this approach: treating an emergency fund as a single undifferentiated block leaves money on the table and creates friction at the worst possible moment. Splitting it into two tiers — one built for speed, one built for growth — resolves the tension that a single account can never fully address. The result is a safety net that responds when it needs to and earns when it doesn't, which is exactly what a well-structured financial foundation is supposed to do.