Most household budgets look reasonable on paper but fall apart in practice — not because the math is wrong, but because the timing is. Bills don't arrive in neat, evenly spaced intervals. Rent, insurance premiums, subscription renewals, and utility spikes tend to cluster together, landing in the same two-week window while your next paycheck is still days away. The result is a cash-flow crunch that feels like a crisis even when your monthly income is technically sufficient.
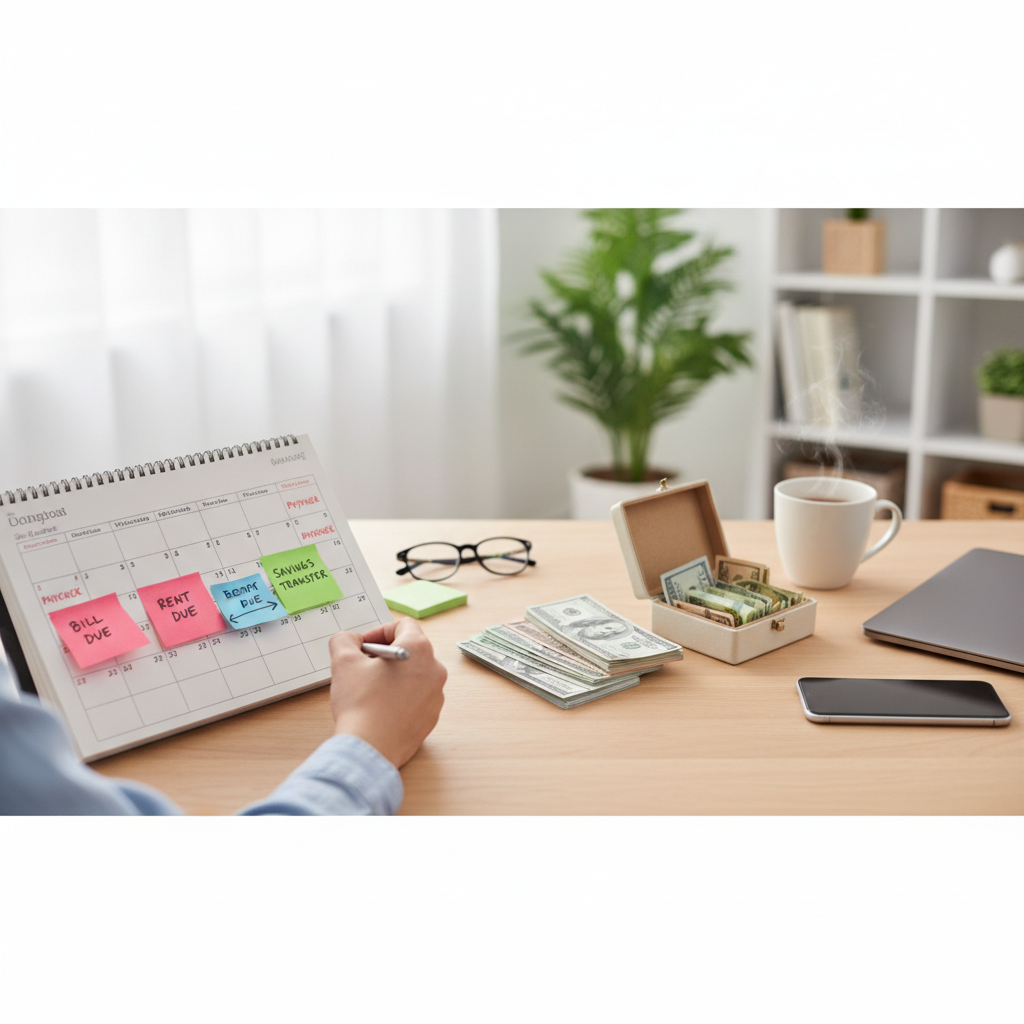
A cash-flow calendar is one of the most practical tools for solving this exact problem. It maps when money actually moves — both in and out — so you can see the gaps before they become overdrafts. Here's how to build one and use it to take control of those rough weeks.
What Does a Cash-Flow Calendar Actually Track?
Unlike a standard budget, which totals income and expenses across an entire month, a cash-flow calendar breaks your finances down by date. You're tracking the specific day each bill is due and each paycheck or payment arrives, not just the category or amount. This week-by-week view reveals something a monthly budget hides: there may be a Wednesday when three bills hit your account simultaneously, followed by a Friday when your paycheck finally clears. That three-day gap is where the damage happens. A calendar makes that gap visible — and once you can see it, you can plan around it.
How Do You Build One From Scratch?
Start with a blank monthly calendar — digital or paper, whichever you'll actually use. Apps like YNAB or Google Calendar work well for this, though a simple spreadsheet is equally effective. List every recurring bill with its due date: rent or mortgage, utilities, insurance, streaming services, minimum debt payments. Then map every income source with the date it lands in your account, not the date it's earned. Once both sides are plotted side by side, patterns emerge quickly. You'll likely see at least one or two weeks where outflows cluster and another stretch where your account has breathing room.
How Can You Shift Bill Due Dates to Reduce the Pressure?
Many billers — credit card companies, utility providers, even some insurers — allow you to request a due date change with a simple phone call or online form. This is one of the most underused cash-flow tools available. If your Citi card payment and your electric bill both land on the 1st, moving one to the 15th spreads the load across the month without changing what you owe. The goal is to distribute obligations more evenly across your pay cycle so no single week carries a disproportionate burden. Even shifting one large recurring bill can meaningfully change how a tight week feels.
What Role Does a Buffer Account Play in Smoothing the Gaps?
A small, dedicated buffer — often called a cash-flow cushion — held in a separate account can absorb the timing mismatches your calendar reveals. The size doesn't need to be large; the equivalent of one week's worth of fixed expenses is often enough to bridge the gap between a bill cluster and an incoming paycheck. Many people keep this in a high-yield savings account at an institution like Marcus by Goldman Sachs or Ally, so the money earns something while it waits. The buffer isn't an emergency fund — it's a timing tool, designed to prevent unnecessary overdraft fees and the stress of watching your balance hover near zero.
How Does Prioritizing Bills by Due Date Prevent Late Fees?
Once your calendar is built, use it to create a payment sequence rather than a flat list of obligations. Bills due in the first week of the month get paid from income that arrived at the end of the previous week. Bills due mid-month get paid from your next paycheck. This sequencing turns an overwhelming pile of obligations into a manageable queue. Late fees are largely avoidable expenses — they exist because payments are forgotten or mistimed, not because the money isn't there. A date-ordered approach eliminates most of them without requiring any additional income.
How Do Irregular Expenses Fit Into a Monthly Calendar?
Quarterly premiums, annual subscriptions, and irregular costs like car registration or dental visits don't fit neatly into a monthly view. The solution is to plot them on the calendar anyway — even the ones that are months away. Knowing that a large insurance premium hits in September lets you begin setting aside a small amount each month starting in the spring, using a sinking fund approach. Irregular expenses only feel disruptive when they arrive unannounced. On a cash-flow calendar, nothing is unannounced.
Why Does Reviewing the Calendar Weekly Matter?
Building the calendar is only half the work. A weekly five-minute review — every Sunday or Monday morning — keeps the picture current. Income timing shifts, new subscriptions appear, and one-off expenses pop up constantly. A calendar you built in January and never updated becomes noise by March. The review habit is what turns a static document into an active financial tool. It also gives you the chance to spot a coming crunch three or four days in advance, which is almost always enough time to transfer money, delay a discretionary purchase, or adjust a payment date.
What Happens When You Combine a Calendar With a Spending Pause?
When the calendar shows a particularly tight week approaching, a short discretionary spending pause — even just three to five days — can preserve enough cash flow to cover the bill cluster comfortably. This isn't a spending freeze or a punishment; it's a deliberate timing choice. Postpone a grocery run until the paycheck clears. Hold off on an online order until the utility bill posts. Small delays in discretionary spending, applied strategically to the specific days your calendar flags as high-risk, have an outsized impact on how smoothly that week passes.
A cash-flow calendar doesn't change your income or eliminate your bills — it changes your relationship to timing, which is where most month-to-month financial stress actually lives. By mapping when money moves rather than just how much, you gain the visibility to make small adjustments before they become urgent ones. The weeks when bills stack up stop feeling like ambushes and start feeling like predictable events you've already planned for.